01 / Federal Opportunity Brief
PACA Special Audits RFQ
02 / Federal Buyer
Who is buying?
03 / Purchase
What is the government buying?
PACA Special Audits RFQ
The current notice is soliciting this requirement from eligible offerors.
The notice describes auditing/performance audit scope including accounting transaction workflows, inter-entity cost allocation methodologies, compliance with SLAs, operational metrics, adequacy of financial management technology system controls, and additional elements tied to electronic gaming data systems (meter reconciliations, cash drop and count controls, payout authorizations, jackpot disbursements, internal control safeguards against manipulation/theft, and IRS Form W-2G processing).
Orders will be issued by the contracting officer, and further details will be provided in specific delivery order project assignments. The notice also describes work being ordered and executed as individual, consolidated performance audit task orders.
Work may be ad hoc and can encompass any Air Force installation, NAF activity, or fund within contract scope, and will be ordered as performance audit task orders (individual and consolidated).
04 / Contracting Requirements
How will this procurement work?
| Requirement | What the notice says | Source status |
|---|---|---|
| Eligibility | No eligibility requirements are stated in the provided evidence. | Not Disclosed |
| Contract ceiling | Not disclosed | Not Disclosed |
| Minimum guarantee | Not disclosed | Not Disclosed |
| Contract duration | Not disclosed | Not Disclosed |
| Foreign participation | Not disclosed | Not Disclosed |
| Proposal and award procedure | The provided evidence does not include submission instructions or detailed evaluation factors/scoring. It only references ordering of audits via task orders and scope content. | Not Disclosed |
| Staffing and security | No staffing levels/qualification requirements or security/clearance requirements are stated in the provided evidence. | Not Disclosed |
Read the original SAM.gov description
General The Air Force Services Center (AFSVC), headquartered at Joint Base San Antonio-Lackland, Texas, delivers Services programs and activities to build and sustain ready and resilient Airmen, Guardians, and families. Air Force Services Center supports bases, major commands (MAJCOMs), and the Air Staff by providing technical expertise, launching new initiatives, developing programs and operational procedures, and managing central support functions. Air Force Services Center ensures the successful operation of essential food services, fitness and sports centers, childcare and youth programs, lodging accommodations, and recreational opportunities for military members and their families worldwide. The Center’s responsibilities include preparing responses to high-level inquiries, providing technical assistance to the field, and developing new programs supporting installation activities. The Financial Management Directorate (VF) centrally manages and administers the Nonappropriated Fund (NAF) Public Accountant Contract Audit (PACA) Program, which supports a worldwide mission providing independent oversight of internal controls, cash management, asset protection, and financial management across the enterprise. Background Nonappropriated Fund (NAF) installations provide support services and activities for military personnel, families, and authorized patrons. Proper management and accountability of Nonappropriated Fund resources are critical to ensuring continued service delivery, operational readiness, and the protection of government interests. Regular independent audits are required to evaluate the financial condition, control environments, and operational efficiencies of Nonappropriated Fund operations. The Air Force Services Center Financial Management, Strategic Policy & Financial Operations Branch (AFSVC/VFSF) exercises central program oversight to ensure compliance with annual statutory audit requirements under Department of Defense Instruction (DoDI) 7600.06, Audit of Nonappropriated Fund Instrumentalities and Related Activities, ensuring adequate audit coverage is provided across the enterprise for Nonappropriated Fund Instrumentalities (NAFIs) Services activities. The term "Activities" refers to operational and revenue-generating entities within the Air Force structure. Audit engagements under this Special Audits contract specifically include financial statement audits and performance audits covering: • Accounting practices and transactional compliance; • Internal control environments and segregation of duties; • Cash management, vault operations, and electronic banking; • Fixed asset accountability, tracking, and depreciation; • Inventory valuation, spoilage controls, and physical counts; • Food and beverage operations and food service portfolios; • Centralized shared service center processing; • Venture gaming and electronic slot machine operations; • Supplemental mission dining operations; and • Agreed-upon procedures and special interest compliance reviews. Specific Focus Areas for the PACA Special Audits Program: • A. Shared Service Center (SSC): Conduct performance audits of the Shared Service Center (SSC) at the Air Force Services Center (AFSVC) located in San Antonio, TX. The primary objective of the performance audit is to address economy, efficiency, and operational effectiveness. The scope includes core accounting transaction workflows, inter-entity cost allocation methodologies, compliance with Service Level Agreements (SLAs), operational metrics, and the adequacy of financial management technology system controls. Further details will be outlined in specific delivery order project assignments. • B. Department of the Air Force (DAF) Venture Gaming Program: The DAF Venture Gaming Program operates electronic gaming and slot machine activities at authorized overseas military installations. The program serves as an important nonappropriated revenue generator utilized directly to support and enhance Morale, Welfare, and Recreation (MWR) programs across all Air Force installations. Authorized by DoDI 1015.10 and centrally managed by AFSVC in San Antonio, TX, slot machine operations present unique risks due to regulatory complexities, high cash volumes, and potential for manipulation. Scope includes electronic gaming data systems, meter reconciliations, cash drop and count controls, payout authorizations, jackpot disbursements, internal control safeguards against manipulation or theft, and compliance with federal tax reporting requirements (including IRS Form W-2G processing). • C. Air Force Cadet Dining Fund: The Cadet Dining Fund is a Supplemental Mission Nonappropriated Fund Instrumentality (NAFI) operated by the 10th Force Support Squadron (10th FSS) located at the United States Air Force Academy (USAFA), Colorado. Supplemental Mission NAFIs receive nonappropriated funds generated from installation mission programs (training, food service, education, security). While congressionally appropriated funds (APF) cover civilian management, custodial services, and facility upkeep, nonappropriated funds are utilized strictly for food purchases and the operational maintenance of cadet meal operations. The fund provides daily dining support for over 4,400 cadets. The Contractor shall perform comprehensive financial statement and operational compliance audits examining food supply procurement, inventory receiving and storage controls, cost-per-meal accounting, meal card verifications, and financial statement accuracy in accordance with USAFAI 34-104 and applicable NAF regulations. • D. Commander’s Special Interest Audits: To address immediate, unplanned operational needs, the Government requires the capacity to execute ad hoc, targeted investigations known as Commander’s Special Interest Audits. These audits may be requested at any given time by Installation Commanders, the AFSVC Commander, or higher headquarters to address immediate operational concerns, suspected material control failures, or strategic risk areas. These ad hoc engagements may encompass any Air Force Installation, NAF Activity, or fund within the scope of this contract, and will be ordered and executed as individual, consolidated performance audit task orders in accordance with the established deliverables and pricing schedules. Scope Air Force Services Center requires the audit services of licensed Certified Public Accountants (CPAs) or CPA firms to perform financial statement audits of Air Force Nonappropriated Fund Instrumentalities (NAFIs) financial statements and performance audits of Nonappropriated Fund Instrumentality (NAFI) Services activities, with particular emphasis on high-risk areas identified through preliminary risk assessments and annual selection matrices.
05 / Historical Spending Trend
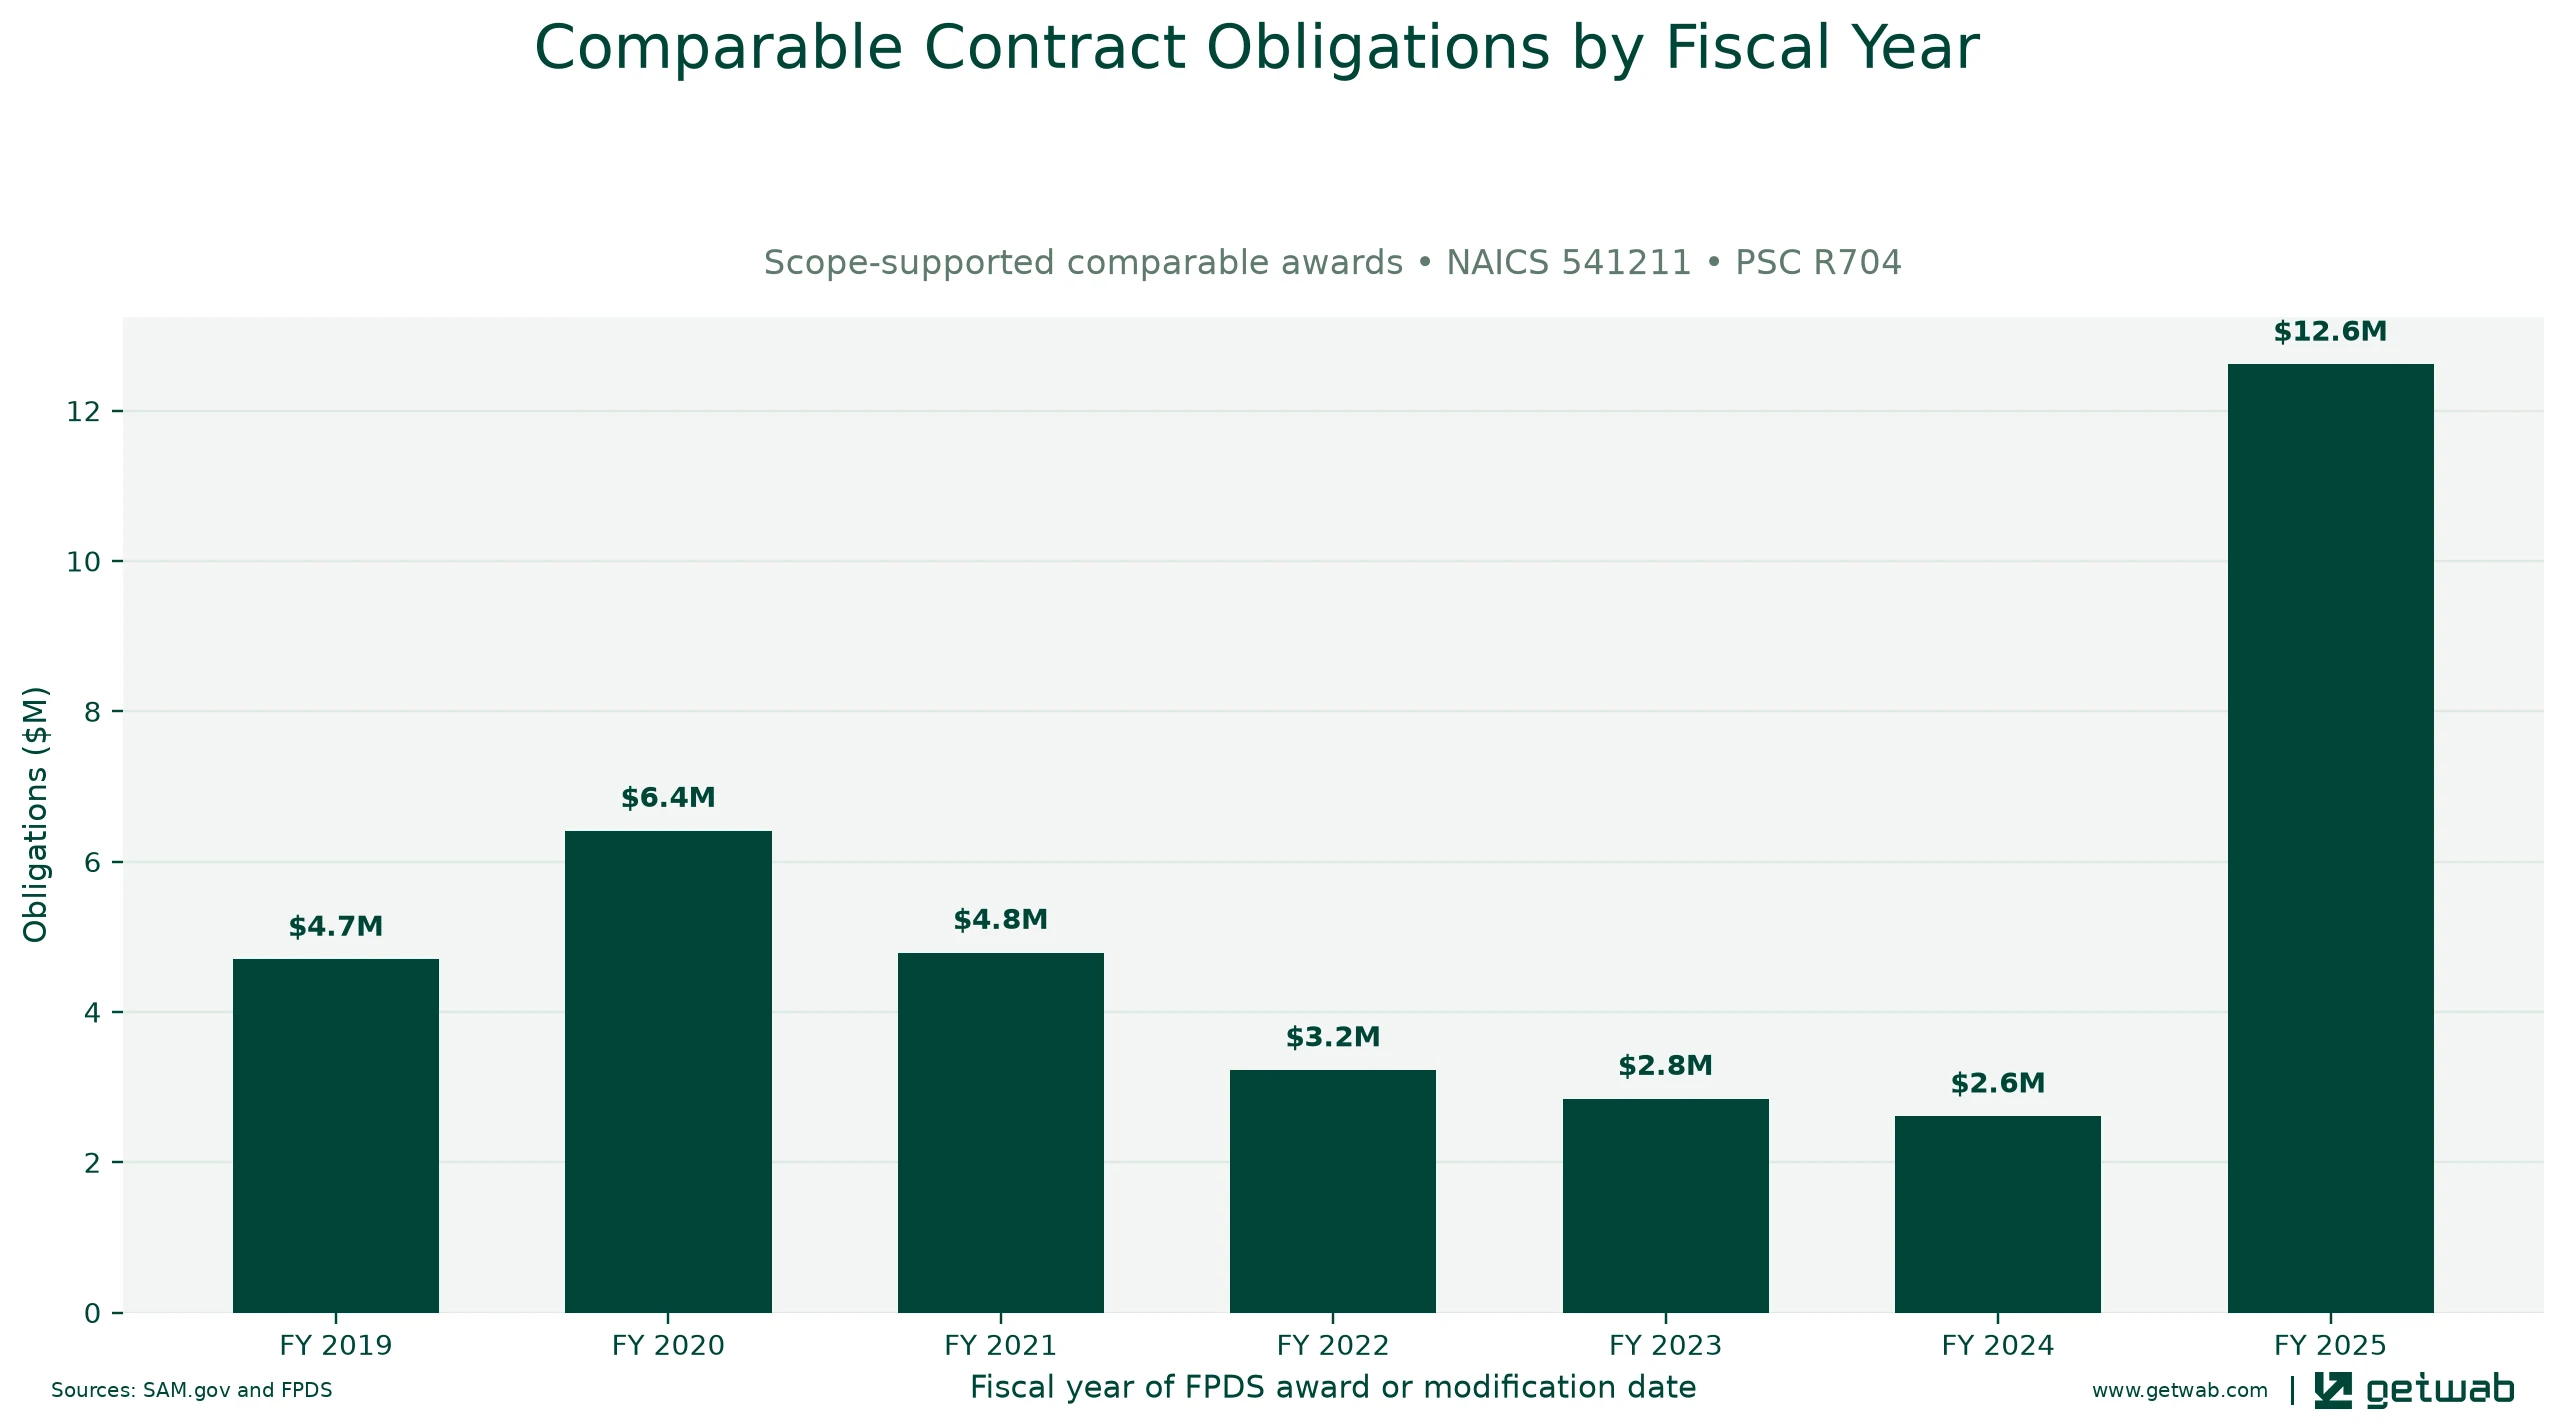
How has spending on the selected comparable contracts changed?
The same closed fiscal-year window and the same complete comparable-contract set are used throughout this Brief. Net obligations total $37.21M across 7 fiscal years.
| Fiscal year | Comparable obligations | Actions | Vendors |
|---|---|---|---|
| FY 2019 | $4.70M | 8 | 4 |
| FY 2020 | $6.41M | 9 | 4 |
| FY 2021 | $4.79M | 3 | 2 |
| FY 2022 | $3.23M | 4 | 3 |
| FY 2023 | $2.85M | 8 | 6 |
| FY 2024 | $2.61M | 8 | 4 |
| FY 2025 | $12.62M | 15 | 7 |
06 / Related Historical Awards
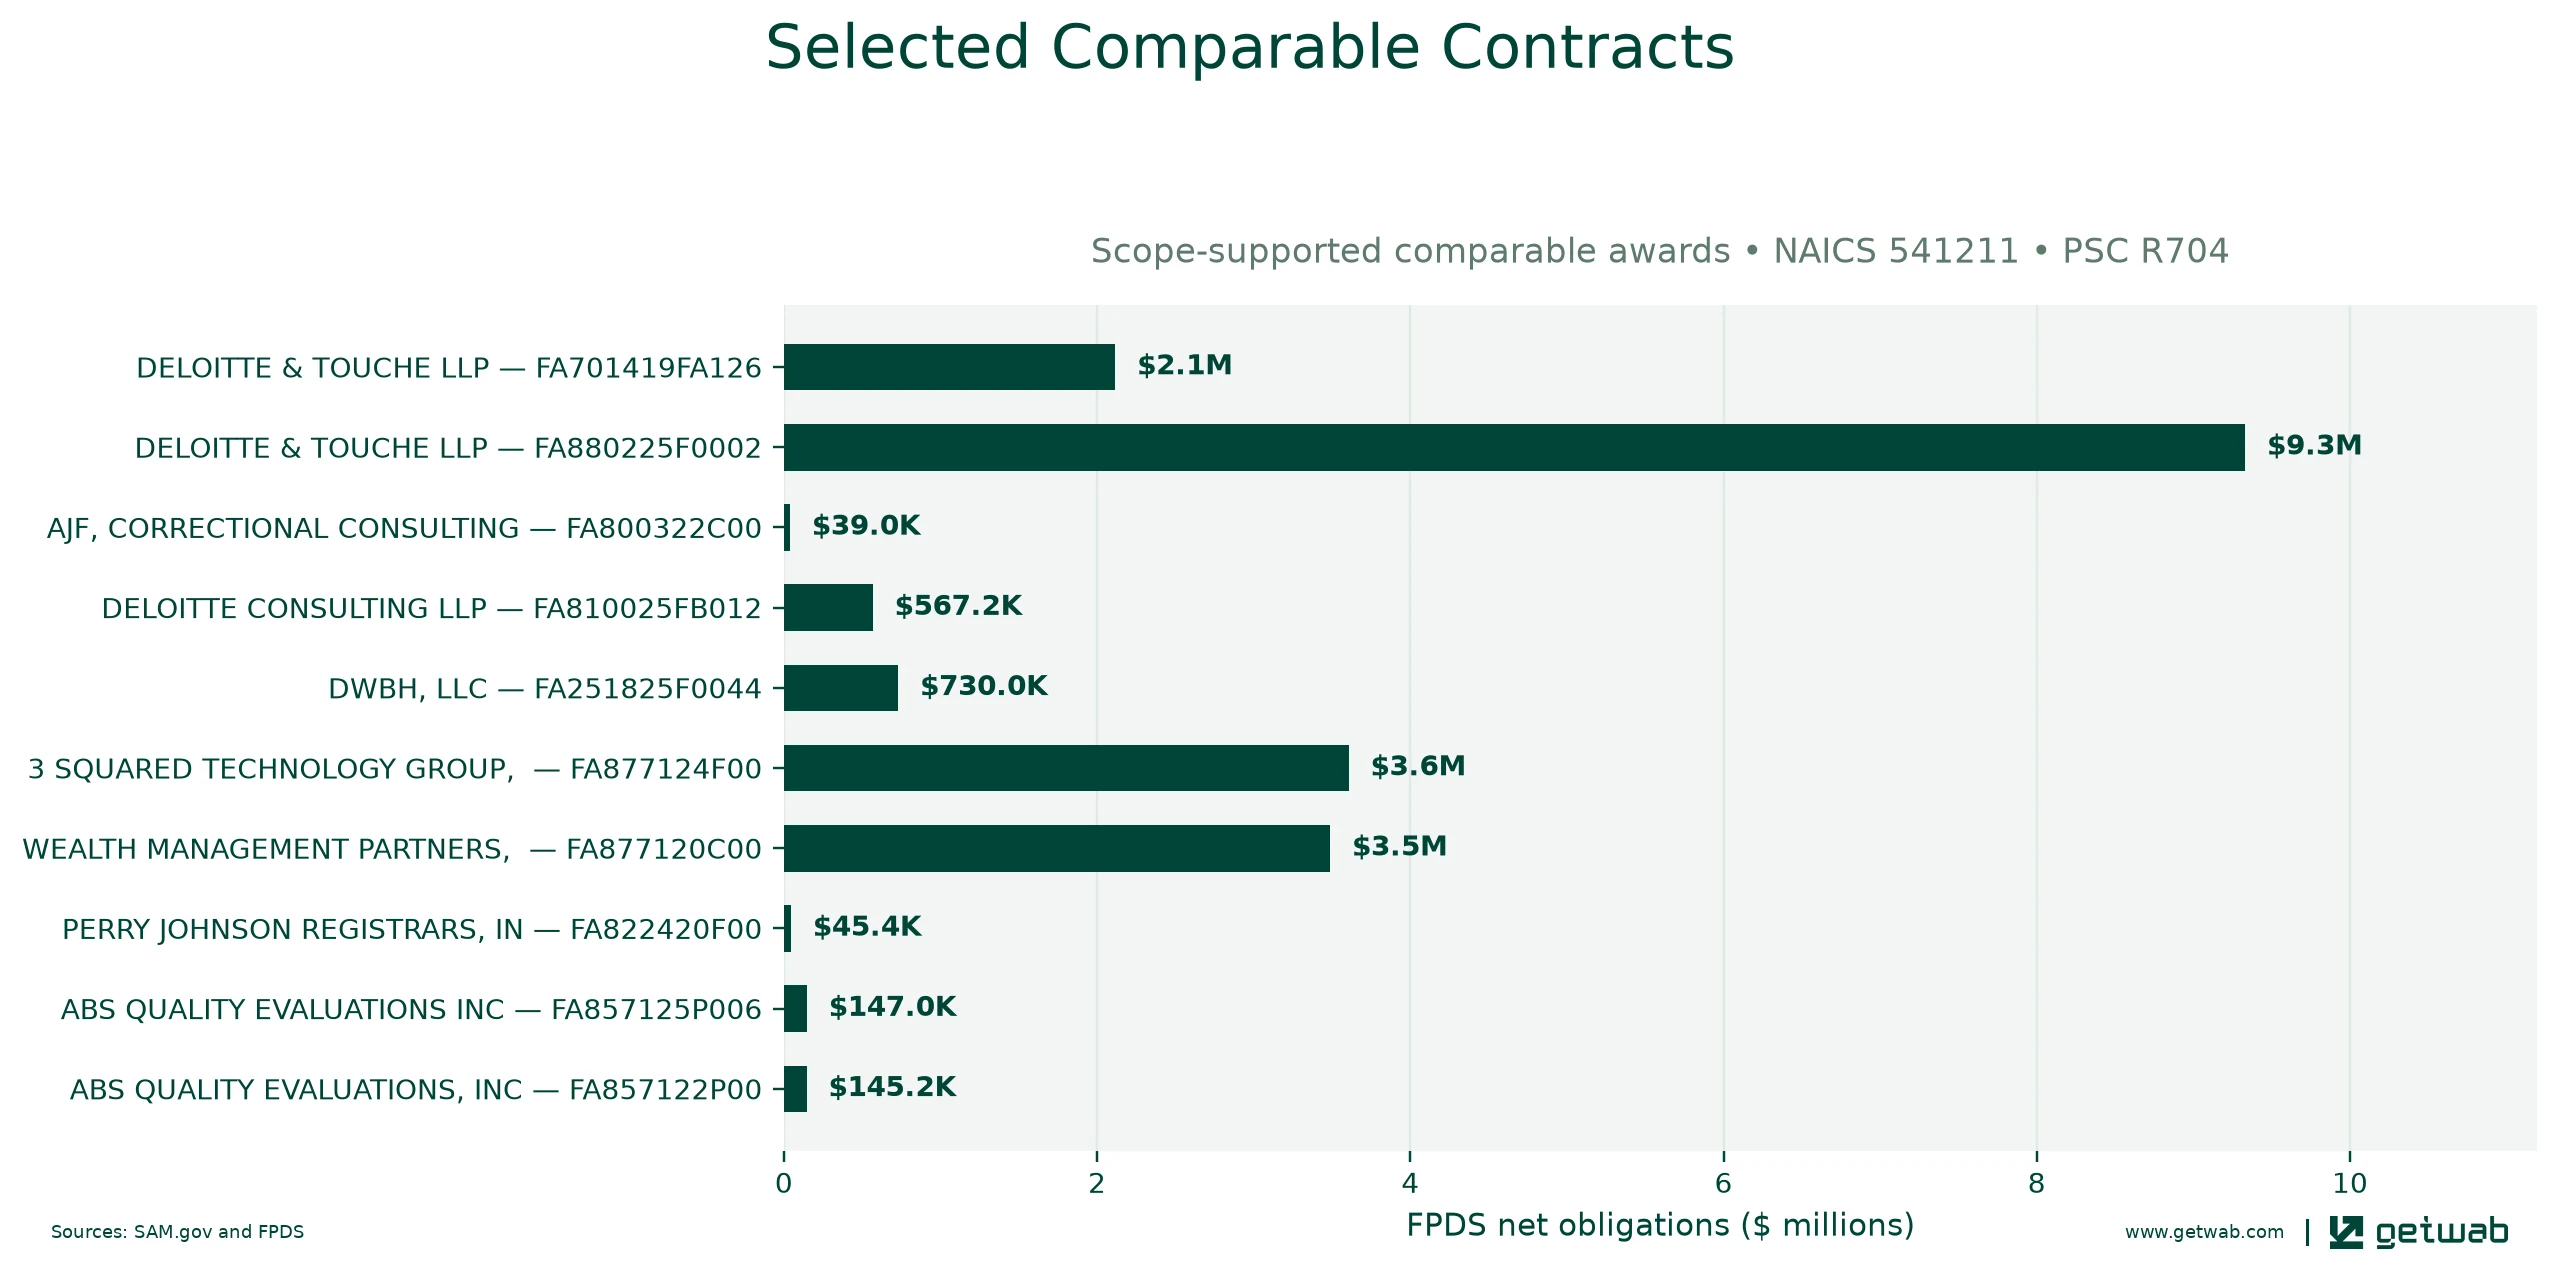
Which contracts support the comparison?
No direct contract reference was found. 15 broad matches are shown as supporting context.
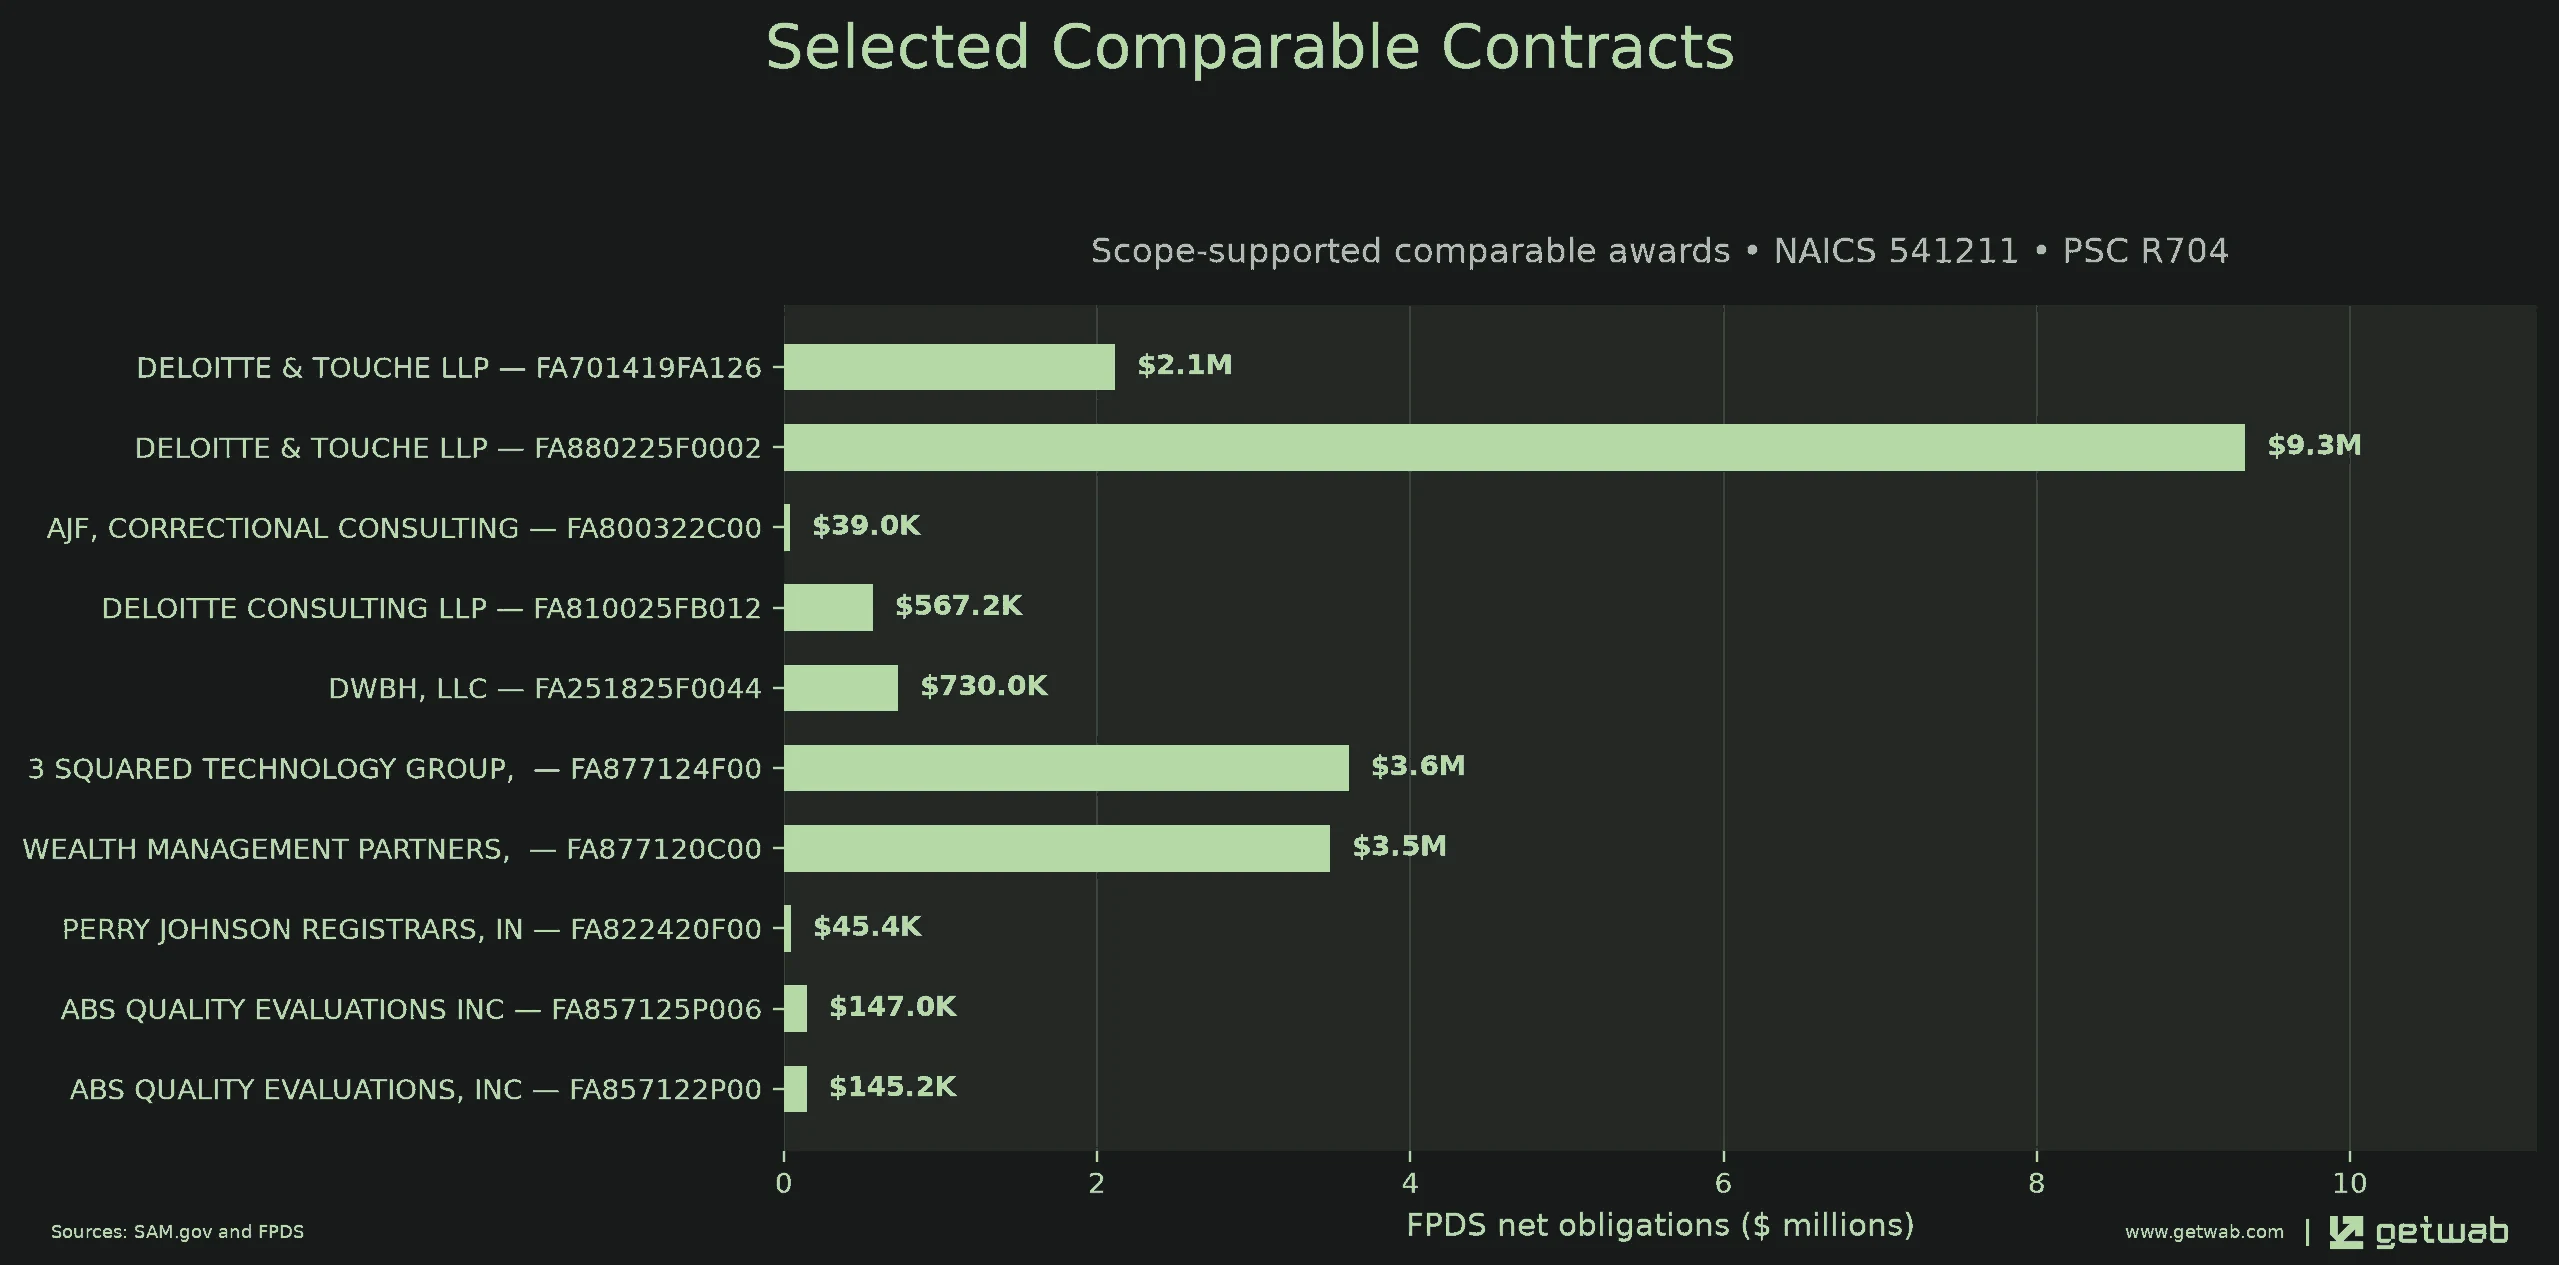
| Contract | Vendor | Latest activity | Office | NAICS / PSC | Match | Obligations | Actions |
|---|---|---|---|---|---|---|---|
| FA701419FA126 | DELOITTE & TOUCHE LLP | Jun 5, 2020 | FA7014 AFDW PK | 541211 / R704 | Broad match Buyer and requirement-language evidence | $2.12M | 1 |
| FA880225F0002 | DELOITTE & TOUCHE LLP | Dec 3, 2025 | FA8802 SSC ENTERPRISE PKA | 541519 / R704 | Broad match Buyer and requirement-language evidence | $9.33M | 8 |
| FA800322C0020 | AJF, CORRECTIONAL CONSULTING & AUDITING, L.L.C. | Jul 26, 2023 | FA8052 773 ESS | 541611 / R704 | Broad match Buyer and requirement-language evidence | $39.0K | 1 |
| FA810025FB012 | DELOITTE CONSULTING LLP | Sep 8, 2025 | FA8100 AFSC PZIEC | 811121 / R704 | Broad match Buyer and requirement-language evidence | $567.2K | 1 |
| FA251825F0044 | DWBH, LLC | Jul 29, 2025 | FA2518 USSF CFC SAIO | 541611 / R704 | Broad match Buyer and requirement-language evidence | $730.0K | 1 |
| FA877124F0040 | 3 SQUARED TECHNOLOGY GROUP, LLC | May 9, 2025 | FA8771 AFLCMC GBK | 541512 / R704 | Broad match Buyer and requirement-language evidence | $3.61M | 2 |
| FA877120C0011 | WEALTH MANAGEMENT PARTNERS, LLC | Feb 6, 2023 | FA8771 AFLCMC GBK | 541611 / R704 | Broad match Buyer and requirement-language evidence | $3.49M | 4 |
| FA822420F0003 | PERRY JOHNSON REGISTRARS, INC. | Oct 2, 2019 | FA8224 AFSC OL H PZIM | 541990 / R704 | Broad match Buyer and requirement-language evidence | $45.4K | 1 |
| FA857125P0064 | ABS QUALITY EVALUATIONS INC | Apr 1, 2025 | FA8571 MAINT CONTRACTING AFSC PZIM | 541611 / R704 | Broad match Buyer and requirement-language evidence | $147.0K | 1 |
| FA813624F0118 | DELOITTE CONSULTING LLP | Oct 16, 2024 | FA8100 AFSC PZIEC | 541611 / R704 | Broad match Buyer and requirement-language evidence | $0 | 1 |
| FA857122P0079 | ABS QUALITY EVALUATIONS, INC. | Mar 23, 2023 | FA8571 MAINT CONTRACTING AFSC PZIM | 541611 / R704 | Broad match Buyer and requirement-language evidence | $145.2K | 2 |
| FA890318F0146 | SEHLKE CONSULTING LLC | Sep 18, 2020 | FA8903 772 ESS PK | 541211 / R408 | Broad match Buyer and requirement-language evidence | $2.34M | 2 |
| FA810017C0020 | GREENTREE GROUP, INC. THE | Aug 24, 2020 | FA8100 AFSC PZIEC | 541211 / R499 | Broad match Buyer and requirement-language evidence | $267.4K | 7 |
| FA301623F0090 | MONBO GROUP INTERNATIONAL, LTD | Dec 18, 2023 | FA3016 502 CONS CL | 541211 / R799 | Broad match Buyer and requirement-language evidence | $359.6K | 1 |
| FA867723FB001 | KPMG LLP | Aug 16, 2024 | FA8677 AFLCMC EBAS | 541211 / R799 | Broad match Buyer and requirement-language evidence | $29.0K | 2 |
07 / Contractor Evidence
Which contractors have performed related work?
Historical contractors are ranked by direct procurement-family evidence and comparable contract activity. The table distinguishes connected holders from broader performers without identifying unverified bidders.
No directly connected predecessor was identified. The companies below are historical performers selected from the comparable contract set; none is identified as a bidder.
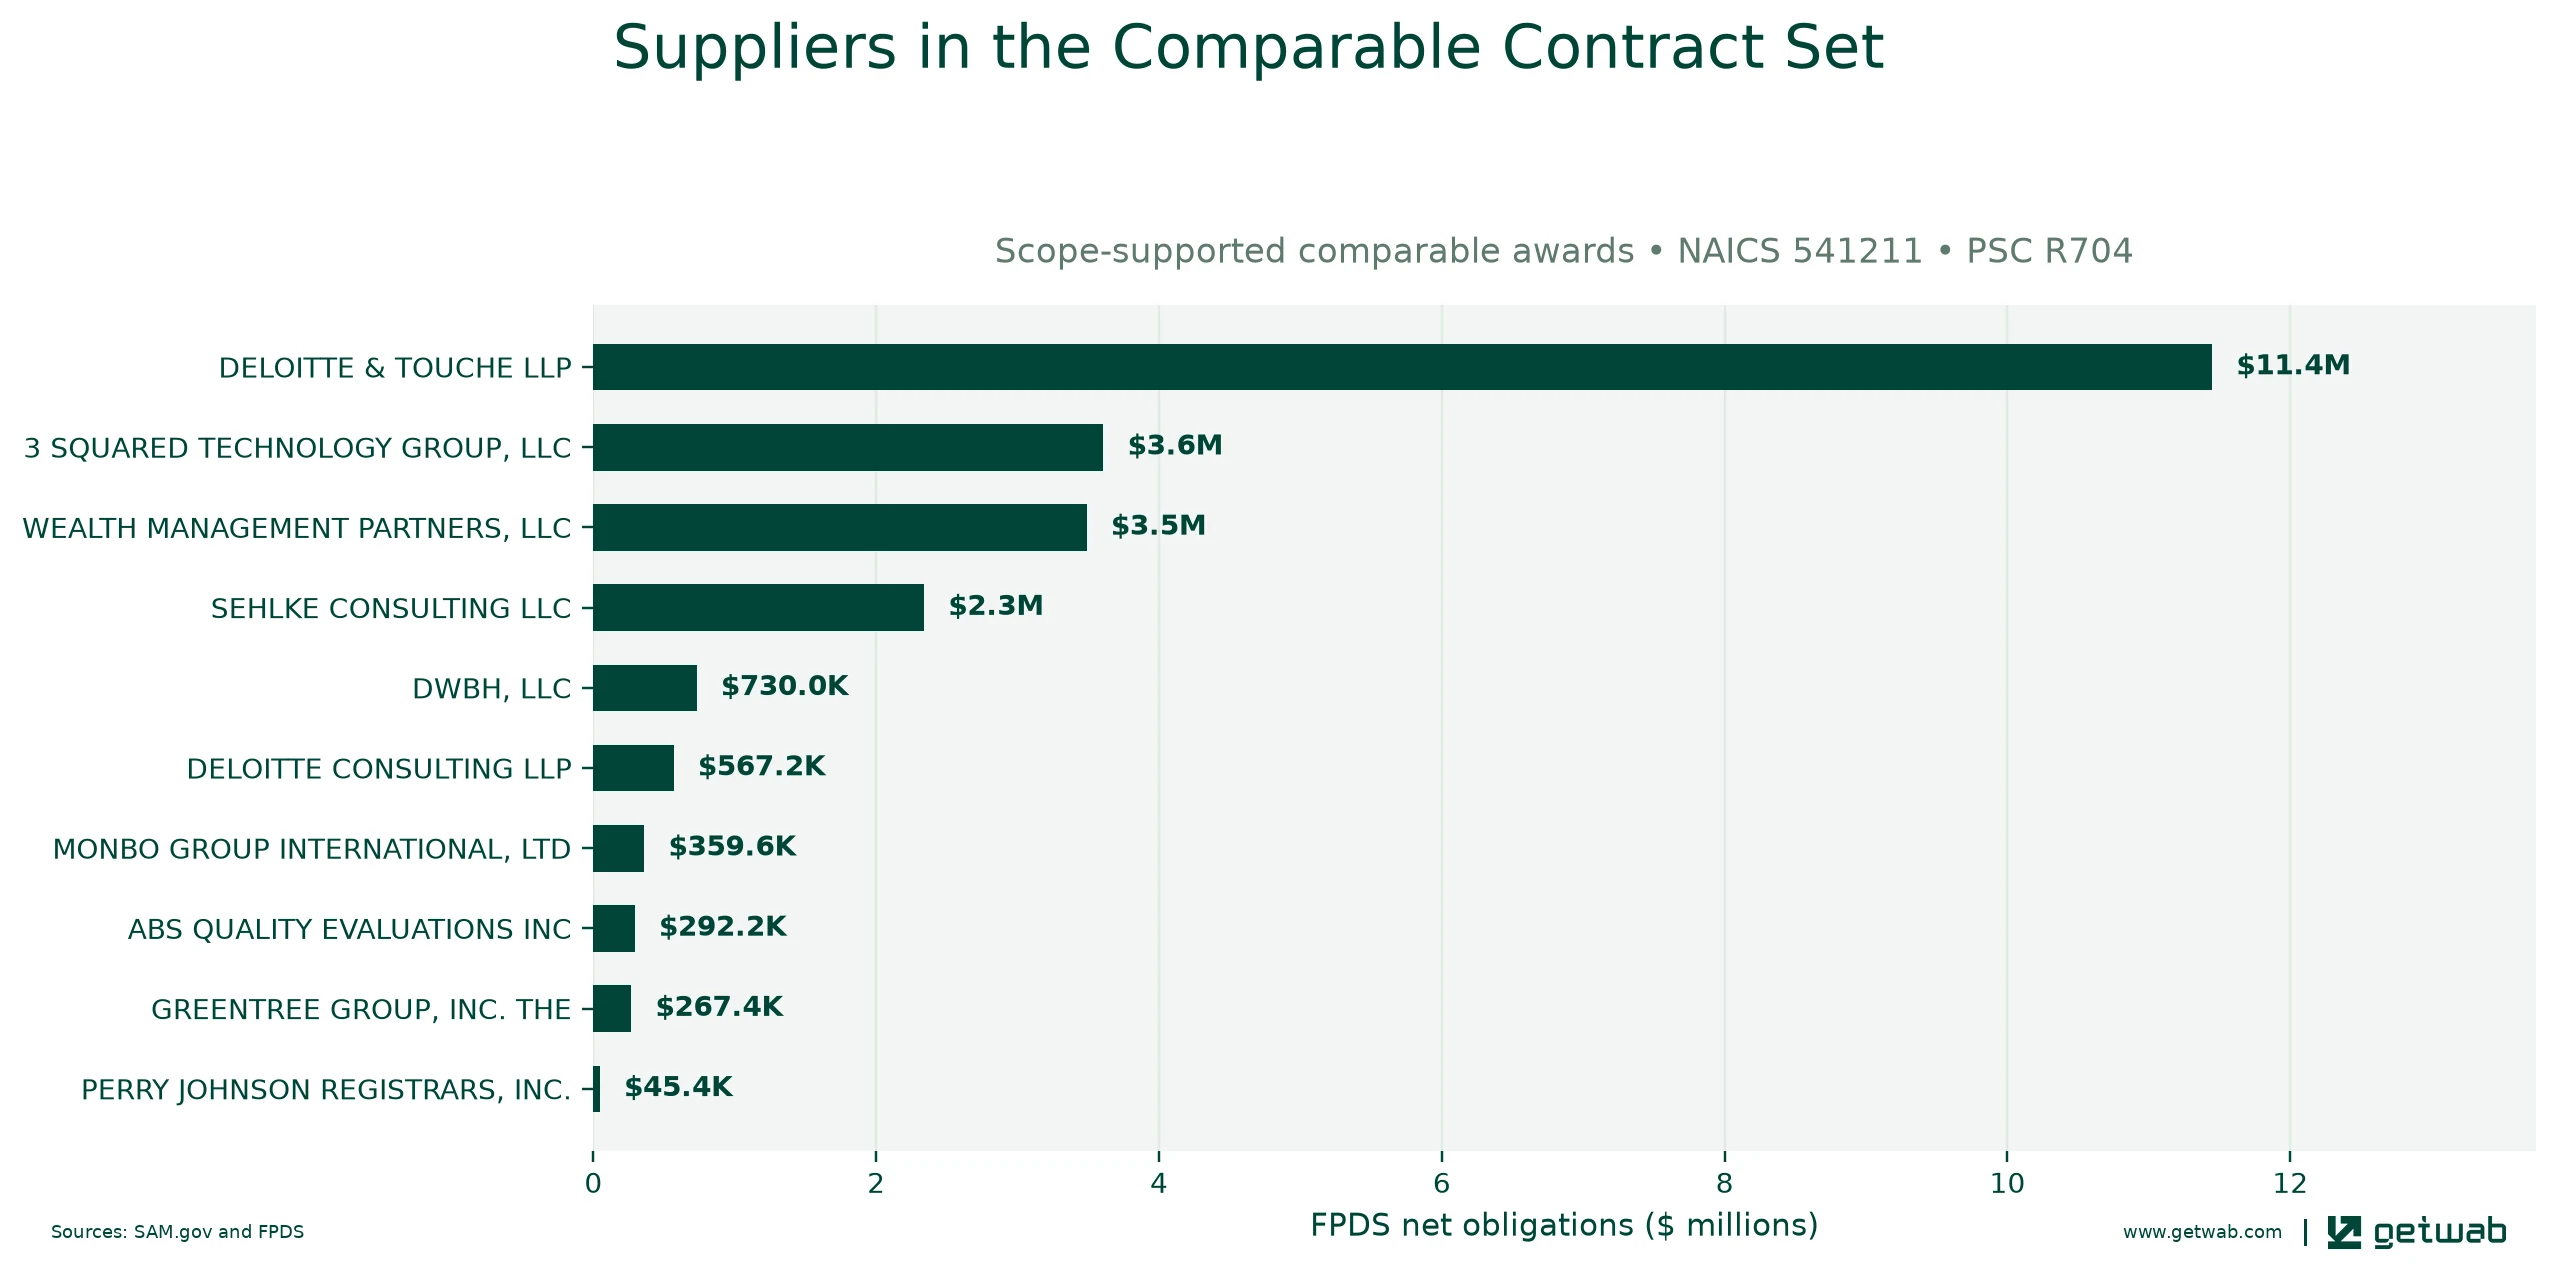
| Company | Evidence | Fit | Why included | Contracts | Actions | Obligations | Latest activity | Links |
|---|---|---|---|---|---|---|---|---|
| DELOITTE & TOUCHE LLP UEI F9KSDU7L9VP6 · CAGE 3CCJ5 | Broad historical performer Historical performer | Moderate | Comparable buyer and requirement history | 2 | 9 | $11.45M | Dec 3, 2025 | GETWAB profile Verified via SAM Entities Official website |
| 3 SQUARED TECHNOLOGY GROUP, LLC UEI MN5MQMJZRKB7 · CAGE 7NTL4 | Broad historical performer Historical performer | Moderate | Comparable buyer and requirement history | 1 | 2 | $3.61M | May 9, 2025 | GETWAB profile Verified via SAM Entities Official website |
| WEALTH MANAGEMENT PARTNERS, LLC UEI NMEBDDB2KZW4 · CAGE 5T3X4 | Broad historical performer Historical performer | Moderate | Comparable buyer and requirement history | 1 | 4 | $3.49M | Feb 6, 2023 | GETWAB profile Verified via SAM Entities Official website |
| SEHLKE CONSULTING LLC UEI E1BDKBCFD2A7 · CAGE 6LRG6 | Broad historical performer Historical performer | Moderate | Comparable buyer and requirement history | 1 | 2 | $2.34M | Sep 18, 2020 | GETWAB profile |
| DWBH, LLC UEI F7TRNHHENB72 · CAGE 6Z1W1 | Broad historical performer Historical performer | Moderate | Comparable buyer and requirement history | 1 | 1 | $730.0K | Jul 29, 2025 | GETWAB profile Verified via SAM Entities Official website |
| DELOITTE CONSULTING LLP UEI CKV2L9GZKJK3 · CAGE 1TTG5 | Broad historical performer Historical performer | Moderate | Comparable buyer and requirement history | 2 | 2 | $567.2K | Sep 8, 2025 | GETWAB profile Verified via SAM Entities Official website |
| MONBO GROUP INTERNATIONAL, LTD UEI FKYVCHTRAMU8 · CAGE 7VJE5 | Broad historical performer Historical performer | Moderate | Comparable buyer and requirement history | 1 | 1 | $359.6K | Dec 18, 2023 | GETWAB profile |
| ABS QUALITY EVALUATIONS INC UEI JYN3YNBE3QJ5 · CAGE 07DR0 | Broad historical performer Historical performer | Moderate | Comparable buyer and requirement history | 2 | 3 | $292.2K | Apr 1, 2025 | GETWAB profile Verified via SAM Entities Official website |
| GREENTREE GROUP, INC. THE UEI NTJGH9RFTS11 · CAGE 04HD7 | Broad historical performer Historical performer | Moderate | Comparable buyer and requirement history | 1 | 7 | $267.4K | Aug 24, 2020 | GETWAB profile Verified via SAM Entities Official website |
| PERRY JOHNSON REGISTRARS, INC. UEI FBGGFQKXSGB7 · CAGE 1LJ60 | Broad historical performer Historical performer | Moderate | Comparable buyer and requirement history | 1 | 1 | $45.4K | Oct 2, 2019 | GETWAB profile Verified via SAM Entities Official website |
| AJF, CORRECTIONAL CONSULTING & AUDITING, L.L.C. UEI PUKCLKWEVZK9 · CAGE 81E48 | Broad historical performer Historical performer | Moderate | Comparable buyer and requirement history | 1 | 1 | $39.0K | Jul 26, 2023 | GETWAB profile |
| KPMG LLP UEI MAA3SBSDQVM1 · CAGE 7QEG9 | Broad historical performer Historical performer | Moderate | Comparable buyer and requirement history | 1 | 2 | $29.0K | Aug 16, 2024 | GETWAB profile Verified via GSA eLibrary Official website |
08 / Competitive Landscape
How was comparable work competed?
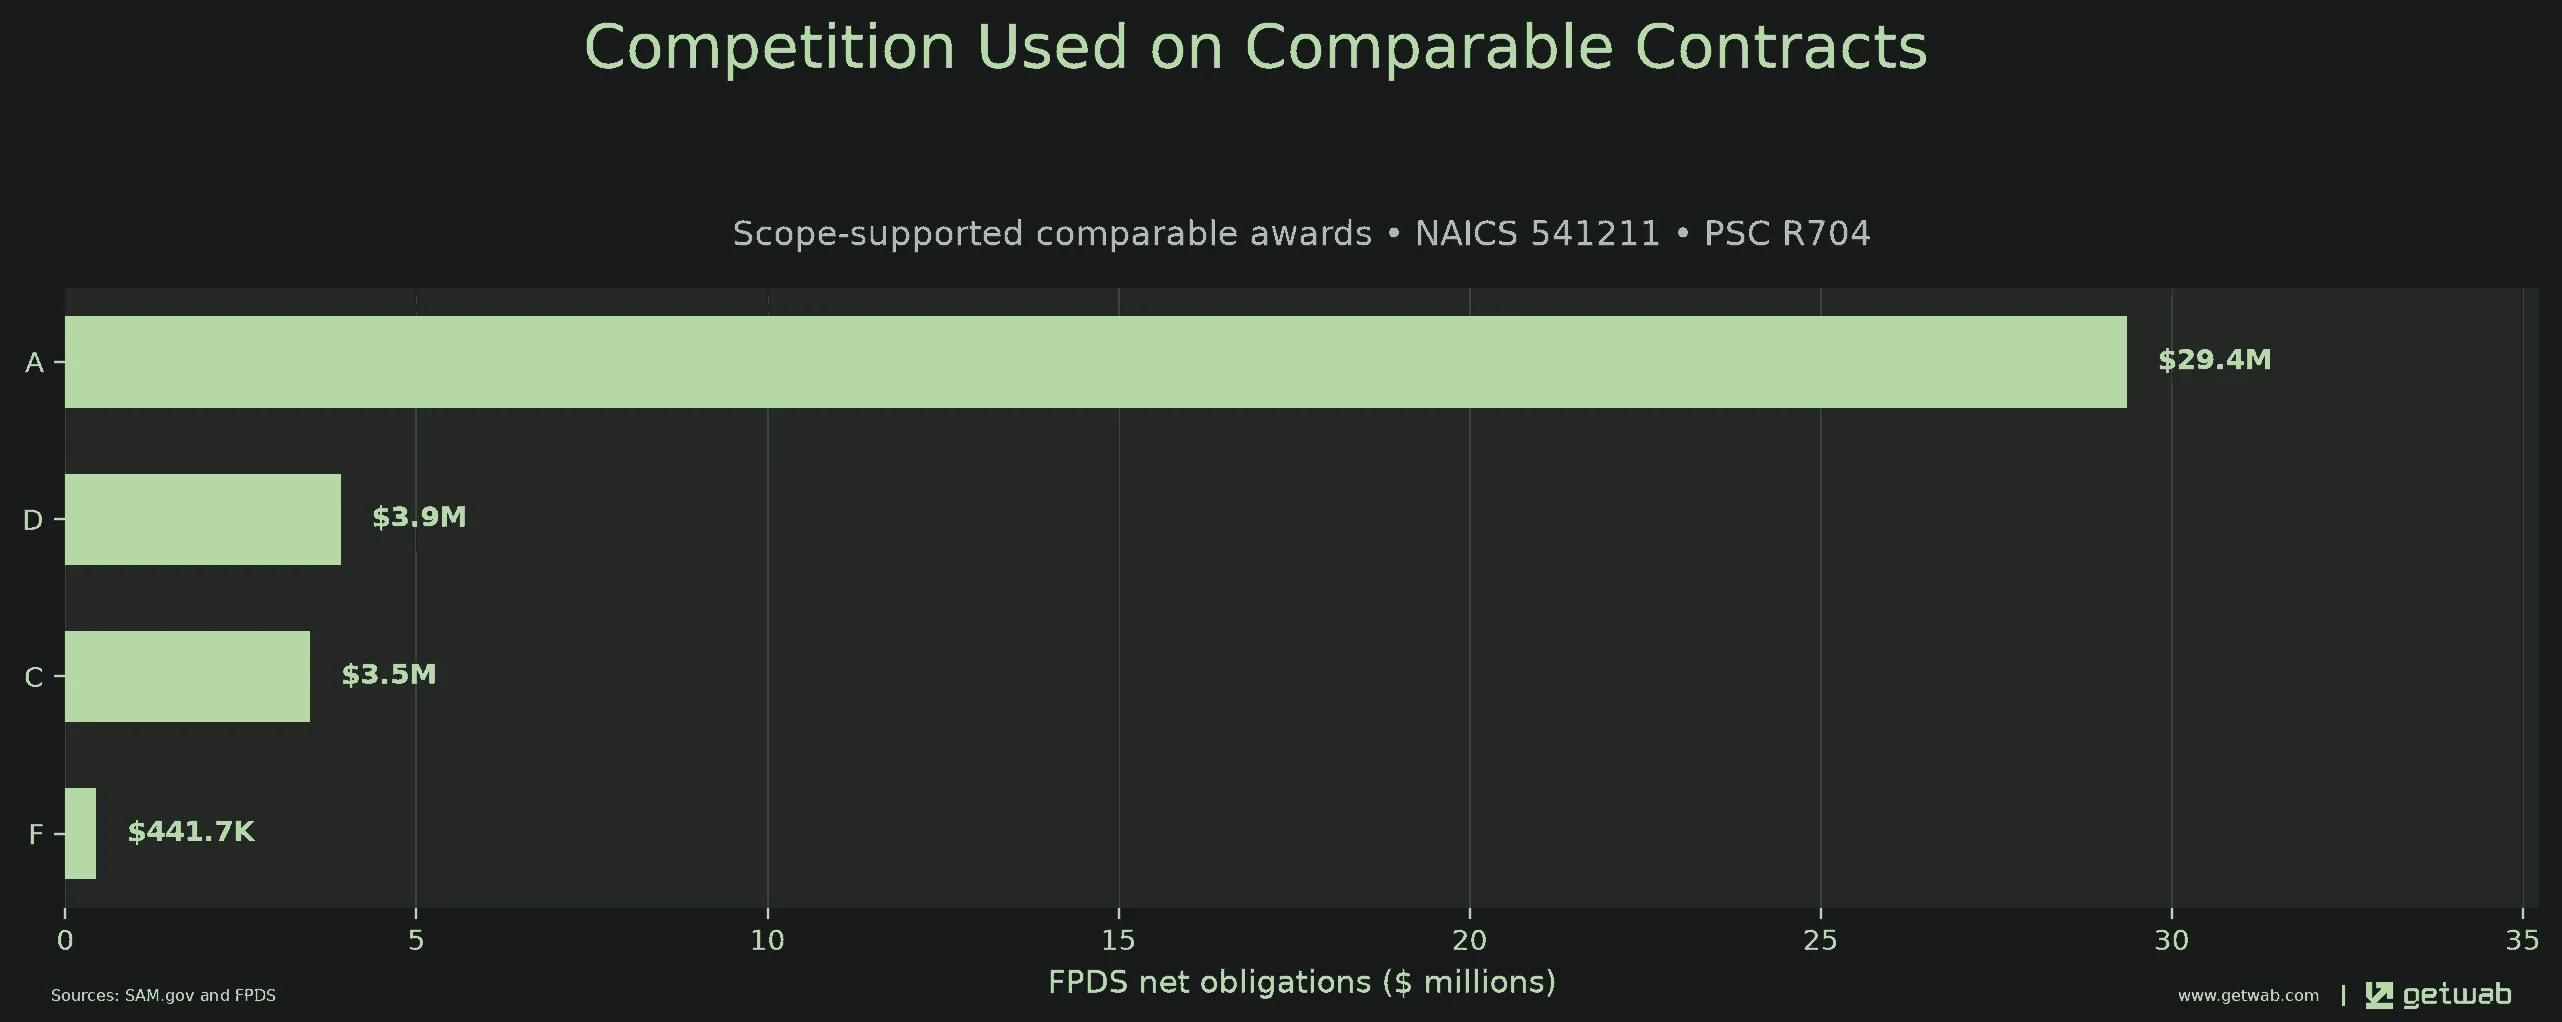
Competition treatment is calculated from exactly the same closed-period contract set used in Sections 5–7. It describes historical actions, not the outcome of this solicitation.
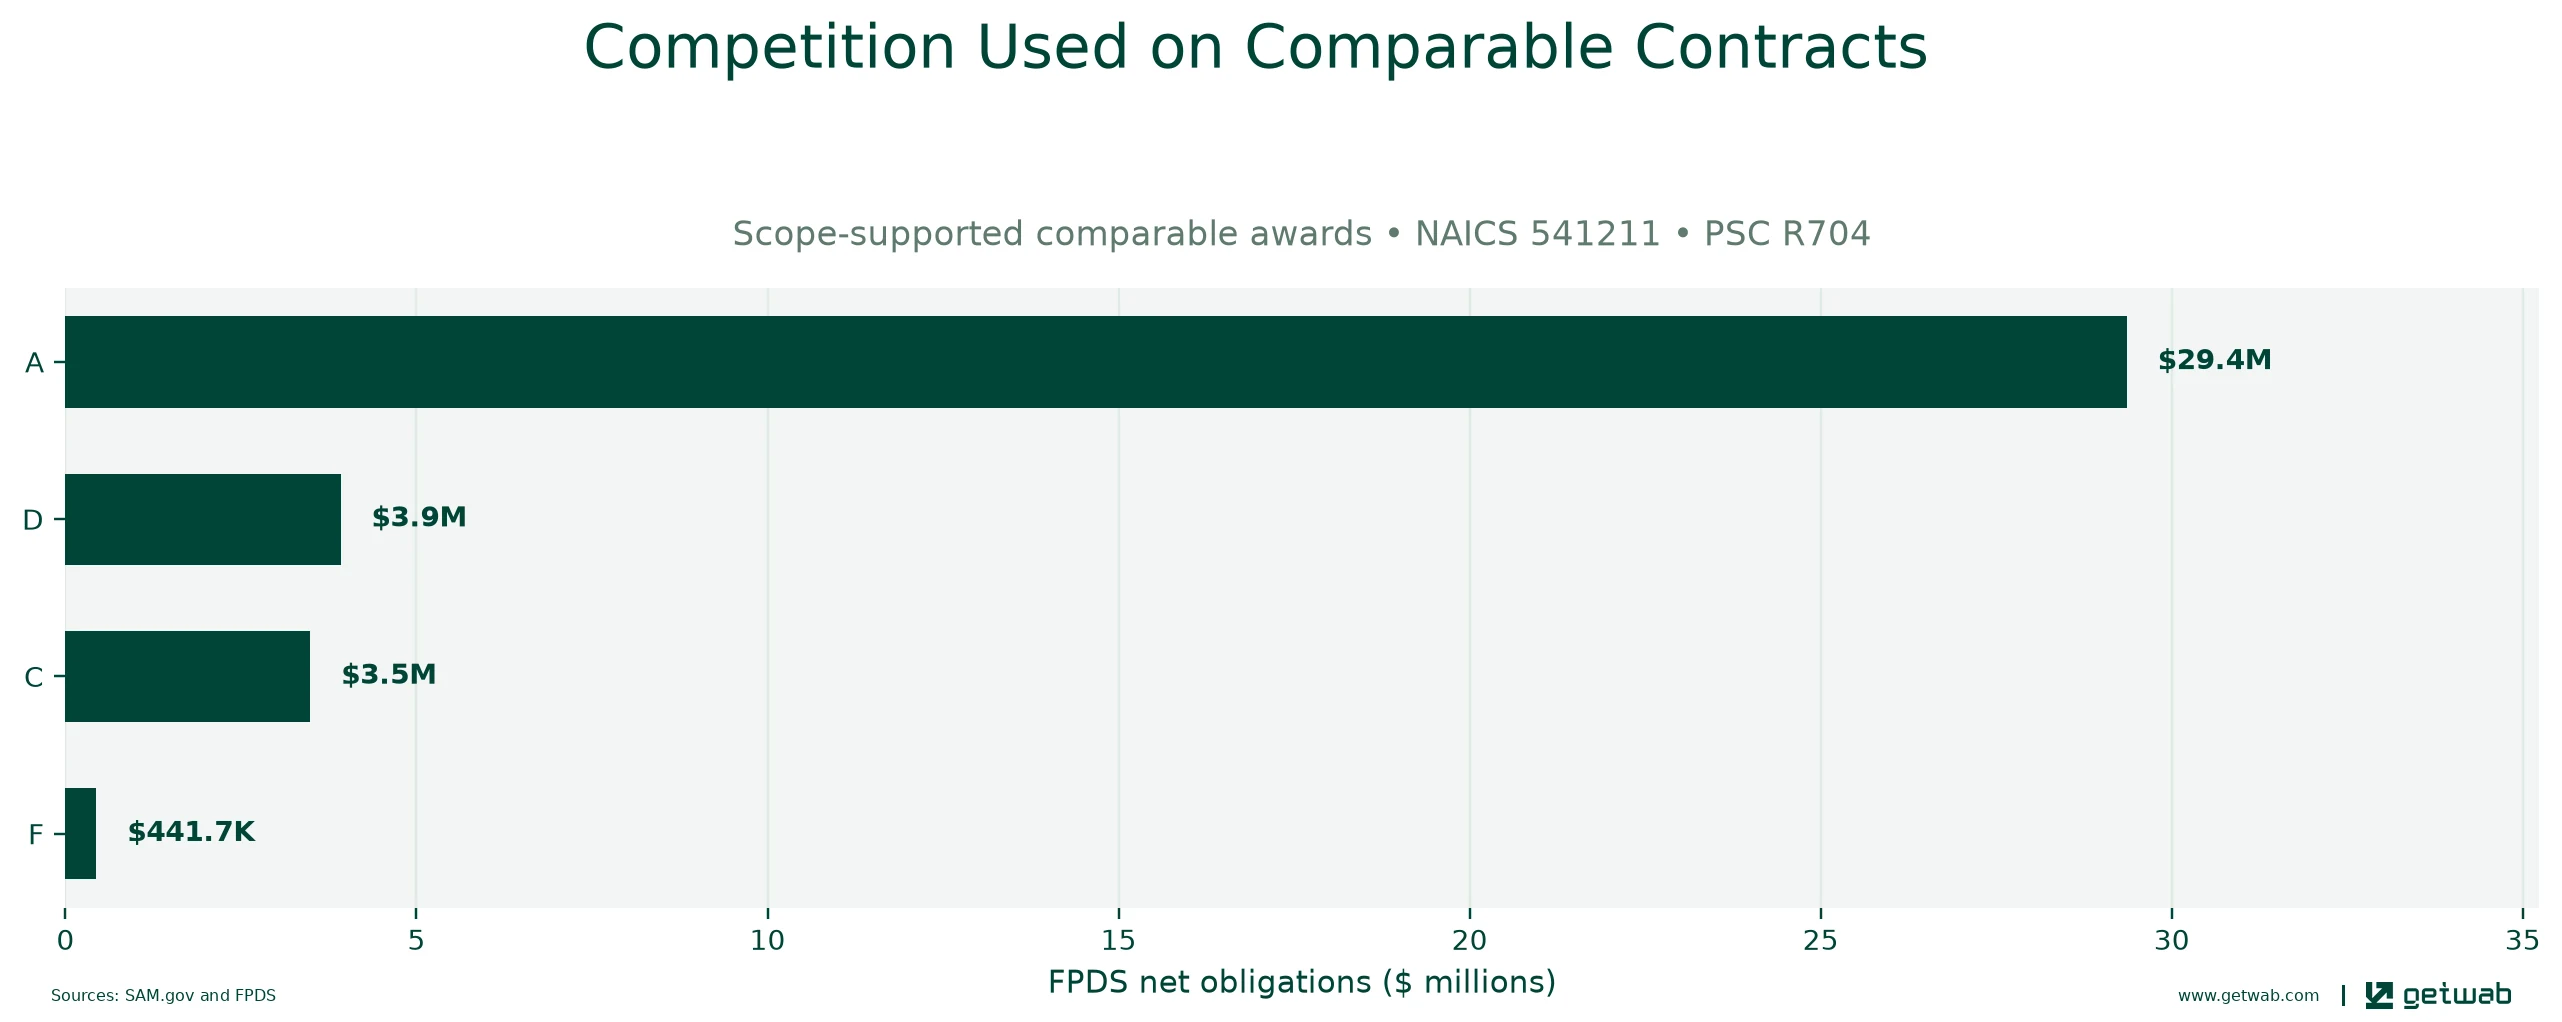
| FPDS treatment | Code | Actions | Obligations | Share |
|---|---|---|---|---|
| Full and open competition | A | 32 | $29.36M | 78.9% |
| Full and open after exclusion of sources | D | 11 | $3.92M | 10.5% |
| Not competed | C | 4 | $3.49M | 9.4% |
| Competed under simplified acquisition procedures | F | 8 | $441.7K | 1.2% |
09 / Procurement History
How was this opportunity published and updated?
One SAM.gov notice record was resolved for this procurement family.
| Notice | Type | Posted | Response deadline | Status | Official source |
|---|---|---|---|---|---|
| F41999-27-Q-0007 Current Brief record PACA Special Audits RFQ | Solicitation | Nov 10, 2026 | Dec 23, 2026 4:00 PM GMT-0600 | Active | View on SAM.gov |
10 / NAICS and PSC Market Context
How large is the selected comparable market?
Classification codes organize the evidence; they do not prove that every contract in the broader NAICS or PSC market matches this requirement.
11 / Capture Signals and Risks
What should be validated before committing capture resources?
Capture signals separate verified procurement-family evidence from unresolved requirements and market-only indicators.
Direct procurement-family evidence
No direct award record found
Buyer proximity
No same-office comparable identified
Eligibility
Not disclosed in the indexed notice
Unresolved requirement fields
7
12 / Who Should Pursue
When does this opportunity fit?
- Your team can demonstrate recent, relevant delivery in PACA Special Audits RFQ.
- You can perform under the stated acquisition model: Orders will be issued by the contracting officer, and further details will be provided in specific delivery order project assignments. The notice also describes work being ordered and executed as individual, consolidated performance audit t
- You can show credible past performance for FA9000 AF NAF PO or a closely related federal customer.
- Your technical scope fits, but you lack demonstrated history with FA9000 AF NAF PO.
- You need a specialist teammate to close unresolved staffing, security, or detailed-scope requirements before committing.
- Your delivery model cannot support the stated contract vehicle or order-based work structure.
- The unresolved requirements shown above cannot be validated before committing proposal resources.